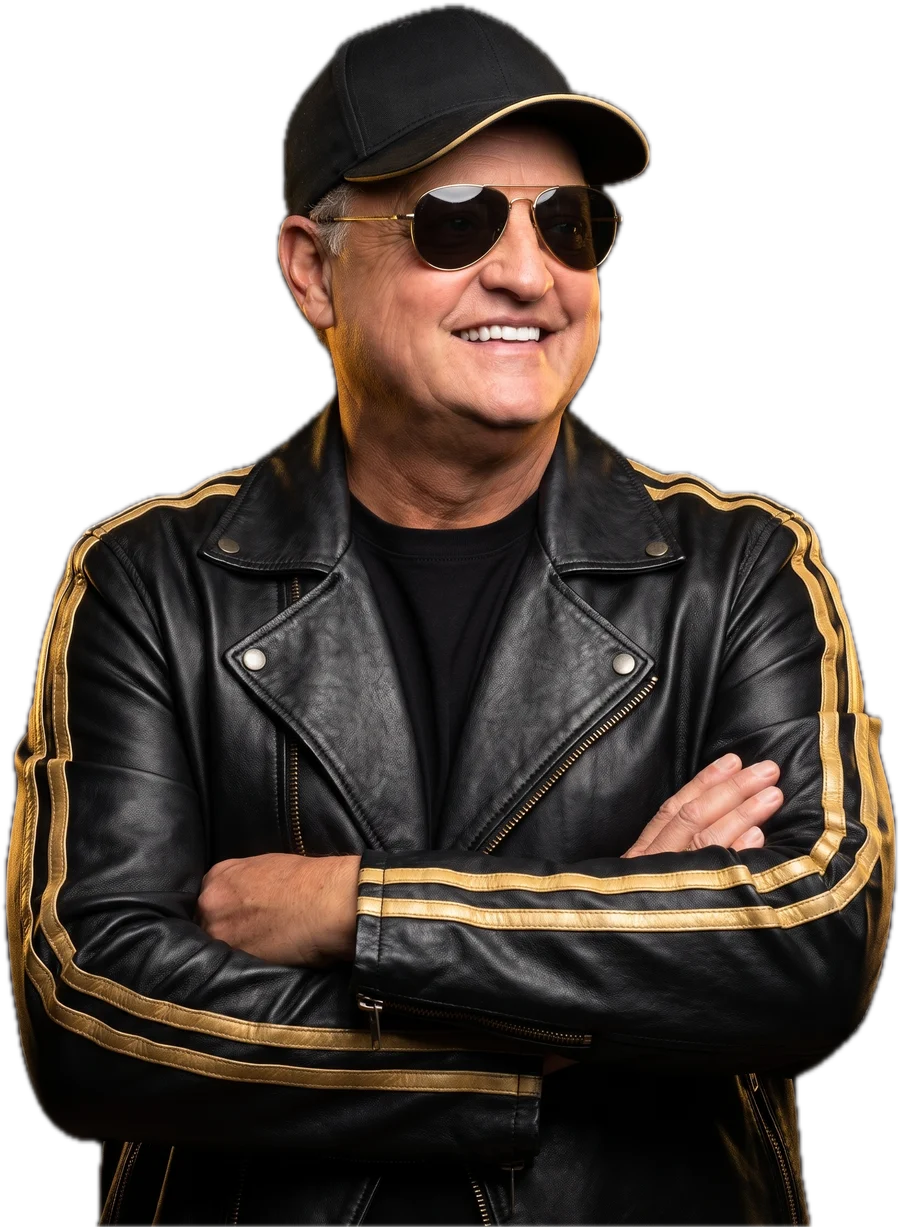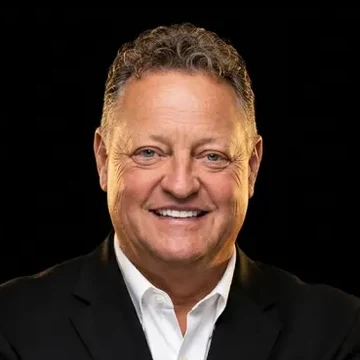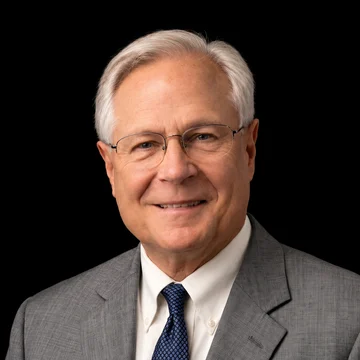
Ron Glover · Retirement Specialist

Buy your fixed index annuity from Ron Glover

Retirees live on income, not savings. Ron is independent, works with fixed index annuities only and shops top-rated carriers for you. The call is free, with straight answers, no fee for our help and no pressure.

  • No market losses*
  • Locked yearly gains
  • Lifetime income
  • Free snapshot
Ron Glover, Retirement Specialist
Carriers we work with
Athene North American F&G EquiTrust

Logos are trademarks of their owners and do not mean any carrier endorses Annuity Advisors Group. Products and availability vary by state.

Plan with clear eyes

Retirement income expert Tom Hegna teaches that retirees don’t live on assets, they live on income. Start with the paycheck you need.

What researchers found

Researchers have studied fixed index annuities and their role in retirement planning, including:

  • Wade Pfau, Ph.D., CFA, on fixed index annuities in retirement portfolios
  • Roger Ibbotson, Ph.D., on fixed index annuities as an option alongside bonds
  • David Babbel, Ph.D., on what real fixed index annuity contracts have credited

Their findings cover certain products, assumptions or data. They are not endorsements of every annuity or a recommendation for every retiree. Some of this research was paid for by financial companies.

Find your paycheck gap

Fill in both to see your gap. Nothing is sent anywhere.
Talk About Closing It

Watch: Don't Worry, Retire Happy

A free video from retirement income expert Tom Hegna. It walks through the choices that shape your retirement, in short pieces.

Watch it, then bring your questions to Ron's team.

Watch the free video

Tell us where to send it, and we will open it for you.

See what an annuity could do for your retirement

Answer a few questions and get your free Guaranteed Income Snapshot. Built for savers with $500,000 or more set aside for retirement.

Step 1 of 4 · Your money
Step 2 of 4 · Your goals and timing
What do you want this money to do?
When would you like income to start?
What worries you most? Pick any
Step 3 of 4 · Your fit preview
Step 4 of 4 · Where to send your full Snapshot

Your answers are private. We never sell your information. See our Privacy Policy and Terms.
You may gain
  • Protection from index losses
  • Income you can't outlive
  • Less selling in a downturn
You may give up
  • Access to every dollar
  • Unlimited market upside
  • Freedom from surrender periods

Know what you're buying before you sign

Six short, free guides on fixed index annuities. Read them before you talk to anyone, Ron included.

"Retirement is a long road trip. It's less about the biggest gas tank and more about knowing you won't run out of gas before you get there."Retirement researchers such as Wade Pfau and Nobel laureate Robert Merton put dependable lifetime income ahead of account size. Naming them does not mean they endorse any product or advisor.

Talk to Ron Glover, the FIA specialist

Get Ron for a free call. He'll show you every number that matters, tell you what can go wrong, and say so plainly when an FIA isn't the right move. Already been pitched one? Bring it.

Ron Glover speaking on stage

Meet Ron's team

Ron GloverRon GloverLicensed Agent
NPN #17168228
GabrielGabrielLicensed Agent
NPN #22135741
DougDougChFC, CLU
Licensed Agent
NPN #689421
LeslieLeslieLicensed Agent
NPN #21569931
How FIAs work · 1 of 4

It is a contract, not a stock.

You make a deal with an insurance company. Your money is never put right into the market.

An agreement with an insurance company

How FIAs work · 2 of 4

You put money in.

Most people move money from a 401(k), IRA or CD. You pick a term, often five to ten years.

401(k)IRACD
Yourcontract
How FIAs work · 3 of 4

Your interest follows an index.

Each year, your interest is based on how an index did, like the S&P 500, up to a limit in your contract.

Gold line: what you are credited, up to the limit

How FIAs work · 4 of 4

Up years count. Down years don’t.

What you earn locks in each year. If the index falls, you earn zero that year. You keep what you had.

Get My Free Snapshot
Fixed index annuityMarket index

Illustration only, using made-up returns. Not a projection of any real product.

1 / 4
Caps & rates · 1 of 5

Four numbers decide what you earn.

Every fixed index annuity uses the same parts. Most people are never shown them clearly.

Cap rate
Participation rate
Spread or fee
Surrender period

Every contract sets its own. Ron shows you yours.

Caps & rates · 2 of 5

The cap is your top limit.

It is the most you can earn in a year. If the index gains more than the cap, you get the cap.

Gains above the cap are not credited

Caps & rates · 3 of 5

Participation is your share.

It is the part of the index gain you are credited. A lower rate means a smaller slice.

Shown as a slice, not a real rate

Caps & rates · 4 of 5

A spread comes off the top.

It is an amount taken off the index gain before you are credited. It lowers what you earn in good years.

Illustration only

Caps & rates · 5 of 5

The years you agree to stay.

That is the surrender period. Take out more than the free yearly amount too early, and you may pay a charge.

Get My Free Snapshot
Surrender periodFree to move

Each year: a free amount you can take out

1 / 5
Income rider · 1 of 4

A paycheck you can’t outlive.

Many fixed index annuities offer an optional income rider. It can pay you for as long as you live.

Lifetime incomePay to the order of you
PaidEvery month
For how longFor life
Rider feeUsually yearly
Income rider · 2 of 4

It grows an income base.

Later, you turn it on as guaranteed income for life. It keeps paying even if the account runs to zero.

GrowThe income base builds
Turn onYou pick the start
For lifePaid as long as you live
Income rider · 3 of 4

Know the trade-offs.

Riders usually carry a yearly fee. The income base is not cash you can take out.

✓Income for life
×Usually a yearly fee
×Income base is not cash
Income rider · 4 of 4

Questions Ron answers on your call.

Ron runs the real payout numbers for your age and start date.

Get My Free Snapshot
How much income would my savings buy?
Is the rider fee worth it?
Can I cover my spouse too?
1 / 4
FIA vs CD vs stocks · 1 of 4

Between a CD and the market.

A fixed index annuity sits in the middle, between a CD and the stock market.

CDFIAStocks

Steady  ·  In between  ·  Full ups and downs

FIA vs CD vs stocks · 2 of 4

Can you lose principal to the market?

A CD: no. A fixed index annuity: no. Stocks: yes.

CDNo
FIANo
StocksYes
FIA vs CD vs stocks · 3 of 4

How each one grows.

A CD pays a fixed rate. An FIA is linked to an index, up to a cap. Stocks get the full ups and downs.

CDFixed rate
FIAIndex, up to a cap
StocksFull ups and downs
FIA vs CD vs stocks · 4 of 4

Income and fees.

An FIA can add income for life with a rider. It often has no yearly fee unless you add one.

Get My Free Snapshot
CDNo lifetime income
FIALifetime income with a rider
StocksSometimes, with fees
1 / 4
Paychecks & playchecks · 1 of 5

Retirees live on income, not savings.

Retirement income expert Tom Hegna teaches that retirees don’t live on assets, they live on income. Savings can be lost in many ways. A paycheck keeps coming.

Your savings
Yourpaycheck

Plan the income first. The rest follows.

Paychecks & playchecks · 2 of 5

Every day is Saturday.

He says the day you retire, every day is Saturday. So you need paychecks for the bills, and playchecks so you can enjoy it.

PaycheckFor the billsEvery month
PlaycheckFor the funTrips, golf, family
Paychecks & playchecks · 3 of 5

The go-go, slow-go and no-go years.

Retirement often comes in three stages. You travel and play early, slow down later, then stay closer to home. Spending often falls as the years go on.

Go-goTravel, golf and fun
Slow-goSlower, closer to home
No-goMostly at home
Paychecks & playchecks · 4 of 5

Don’t live a just-in-case retirement.

Tom Hegna tells of retirees who never spent their money, just in case. Then their kids did. A plan lets you enjoy what you saved.

✓Know your paycheck
✓Plan your playchecks
✓Then enjoy your retirement
Paychecks & playchecks · 5 of 5

Plan your paycheck.

Your free Snapshot is a simple place to start. Ron walks you through it on a short, no-pressure call.

Get My Free Snapshot
Lifetime incomePay to the order of you
PaidEvery month
For how longFor life
Rider feeUsually yearly
1 / 5
FAQ & fit check · 1 of 5

Can I lose money?

Not from market drops. You can lose money if you leave early and pay a surrender charge. Rider fees can lower your value in years the index earns nothing.

Protection from market drops

FAQ & fit check · 2 of 5

How does Ron get paid?

The insurance company pays a commission built into the product. There is no separate fee to you, and your full deposit goes into the contract.

No separate fee to you

FAQ & fit check · 3 of 5

Often a good fit if you…

If most of these sound like you, it may be worth a look.

✓Are within ten years of retirement, or retired
✓Can’t afford another 2008-style drop
✓Want more growth potential than CDs
✓Won’t need this money for the term
FAQ & fit check · 4 of 5

Probably not for you if you…

Be honest with yourself here. That is how you avoid a bad fit.

×May need most of the money soon
×Want every bit of market upside
×Have no emergency fund outside it
×Were told it has no downside
FAQ & fit check · 5 of 5

What if the insurer fails?

Guarantees depend on the insurer’s claims-paying ability. Each state also has a guaranty association that covers annuities up to a set limit.

Get My Free Snapshot

That is why Ron focuses on highly rated carriers

1 / 5

Paychecks and playchecks

These ideas come from the teaching of retirement income expert Tom Hegna. Naming him does not mean he endorses any product or advisor.

Live on income, not assets

Retirees don't live on assets, they live on income. Savings can be lost, spent or shrink in a downturn. A steady paycheck keeps coming, so plan the income first.

Every day is Saturday

Once you retire, every day is Saturday. You need paychecks for the bills, and playchecks so you can enjoy the time you worked for.

The go-go, slow-go and no-go years

Retirement often comes in three stages: active early years, slower middle years, and later years spent mostly at home. Spending often falls as the years go on.

Don't live a just-in-case retirement

Some retirees never touch their money, just in case, and never enjoy it. A plan helps you know what you can spend and still feel safe.

How a fixed index annuity works

It is a contract with an insurance company. It is not a stock, and your money is never invested directly in the market.

1. You make a deposit

A lump sum, often a rollover from a 401(k), IRA or CD. You pick a term, usually five to ten years.

2. Interest tracks an index

Each year, your interest is based on how an index like the S&P 500 did, up to a limit set in your contract.

3. Gains lock in

What you earn is locked in every year. If the index falls, you earn zero that year, but you don't lose what you already had.

Illustration only, using made-up returns. Not a projection of any real product.

The 4 numbers that decide what you earn

Every fixed index annuity is built from the same parts. Most people are never shown them clearly.

Cap rate

The most you can earn in a year. If the index gains more than the cap, you get the cap.

Participation rate

The share of the index gain you are credited. A lower rate means you keep a smaller slice of each gain.

Spread or fee

An amount taken off the index gain before you are credited, which lowers what you earn in good years.

Surrender period

The years you agree to stay in. Taking out more than the yearly free amount early can cost a surrender charge.

A paycheck you can't outlive

Many fixed index annuities offer an optional income rider. It grows an income base you can later turn on as guaranteed income for life, even if the account itself runs to zero.

Riders usually carry a yearly fee, and the income base is not cash you can withdraw. Ron runs the real payout numbers for your age and start date.

Questions Ron answers on your call

FIA vs CD vs stocks

A fixed index annuity sits between a CD and the stock market.

CD or MYGAFixed Index AnnuityStocks or Variable Annuity
Can you lose principal to the market?NoNoYes
How growth is setFixed rateLinked to an index, up to a capFull market ups and downs
Upside potentialLow, but certainModerateHighest
Lifetime income optionNoYes, with an income riderSometimes, with fees
Tax treatmentCD taxed yearly, MYGA deferredTax-deferredVaries
Typical ongoing feesNoneOften none, unless you add a riderOften higher yearly fees

Is an FIA right for you?

Often a good fit if you

Probably not for you if you

FIA FAQ

Can I lose money in a fixed index annuity?

Not from market drops. You can lose money by surrendering early and paying a surrender charge, and rider fees can reduce your account value in years the index earns nothing.

Will I get the full S&P 500 return?

No. In exchange for the zero floor, gains are limited by a cap, a participation rate or a spread.

How long is my money tied up?

Most contracts run five to ten years. Most let you take out a part of it each year without a penalty, and many waive charges for nursing home care, terminal illness or death.

Can I roll my 401(k) or IRA into one?

Yes. A direct rollover or transfer keeps the money tax-deferred, with no tax due at the time of the move.

How does Ron get paid?

The insurance company pays a commission built into the product. There is no separate fee to you, and your full deposit goes into the contract.

What if the insurance company fails?

Guarantees depend on the claims-paying ability of the insurer, which is why Ron focuses on highly rated carriers. Each state also has a guaranty association that covers annuities up to a set limit.

Is the money taxed?

Growth is tax-deferred until you withdraw it. Withdrawals of gains are taxed as ordinary income, and before age 59½ may carry an IRS penalty.